CoreWeave Drops Unsecured Bonds and Leans on Customer Prepayments While Microsoft Reviews Its Neocloud Contracts
CoreWeave told investors Nov. 10 that secured loans and about $9 billion of customer prepayments will fund its builds, while Bloomberg reports that Microsoft, 36 percent of its Q2 revenue, is reviewing neocloud contracts.
By Ryan Elliott Dennis · 7 sources · 7 min read
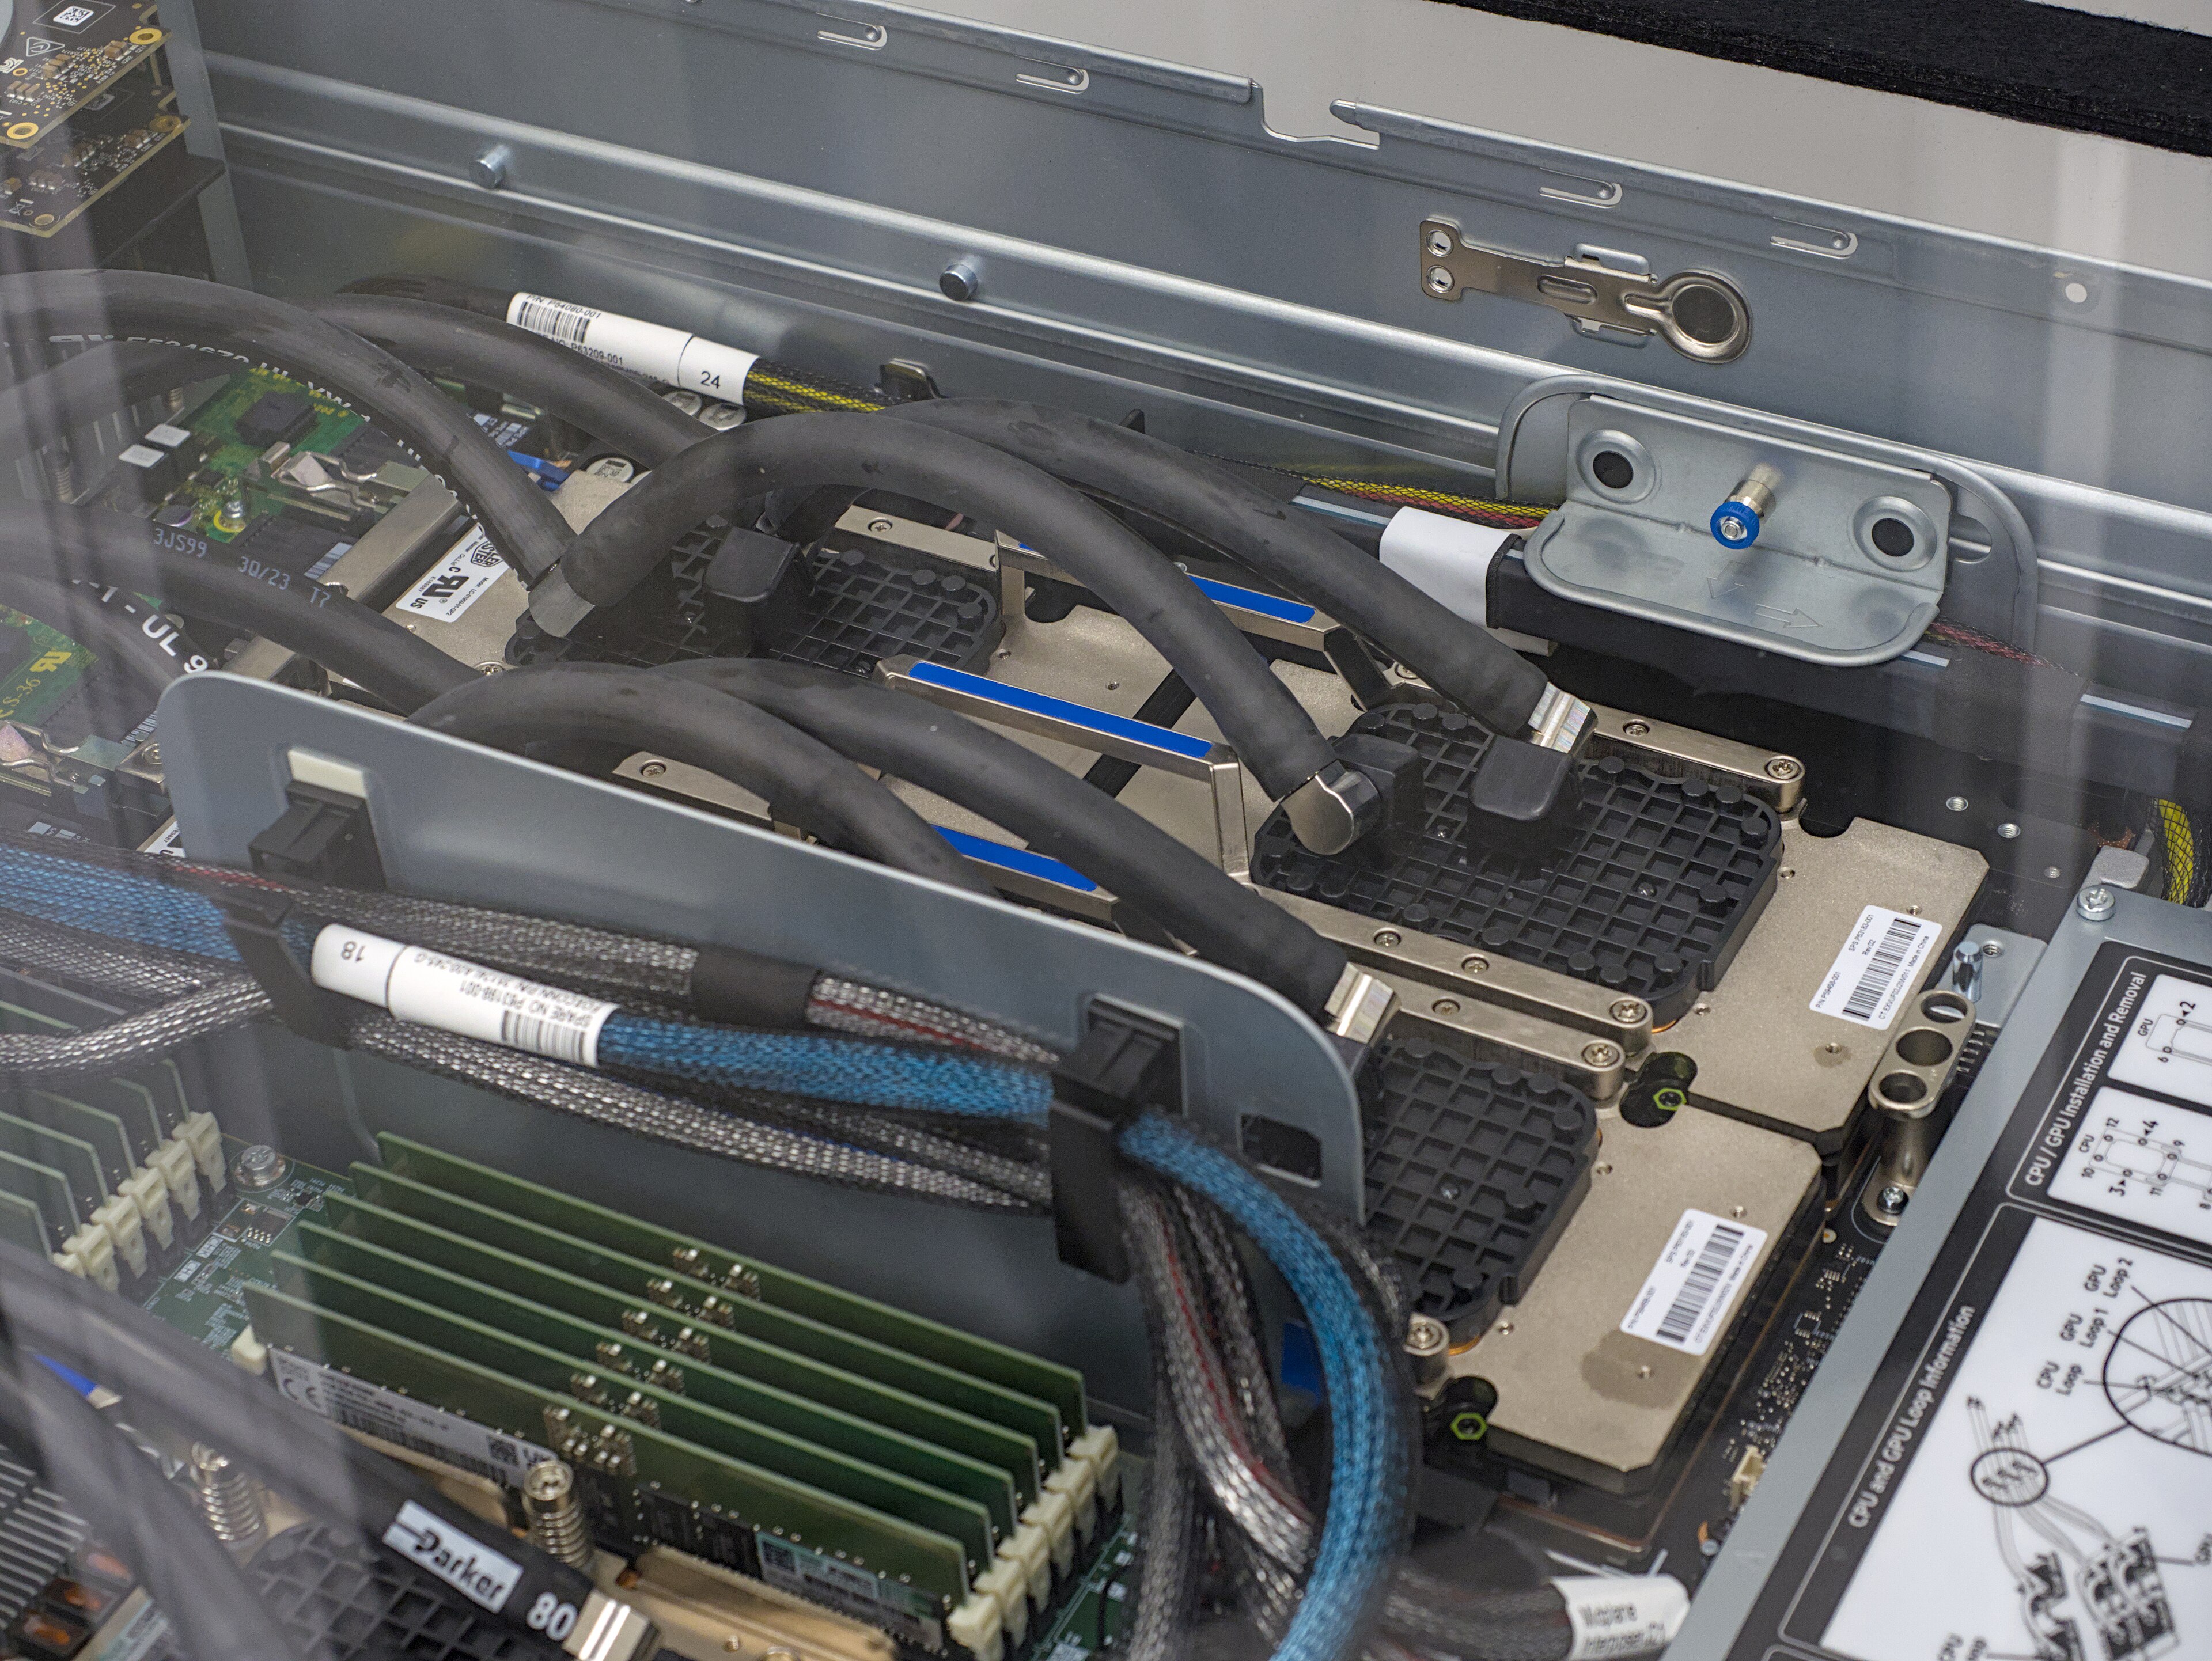
CoreWeave reported third-quarter results on Nov. 10, 2026, and Chief Executive Michael Intrator said secured lending, customer prepayments and operating cash flow will fund the company's build 1. Revenue reached $3.66 billion against $1.37 billion a year earlier. Net interest expense reached $846 million, and operating income was $207 million. Total debt stands near $46.9 billion.
One customer sits behind much of that debt. Microsoft supplied 36 percent of CoreWeave's revenue in the second quarter, according to Motley Fool 6. Bloomberg reported on Nov. 6 that Microsoft, which has committed more than $80 billion to outside cloud providers including CoreWeave, Nscale and Nebius, is reassessing those contracts, per The Next Web 5. So who sets CoreWeave's price of money once the company stops selling unsecured bonds?
CoreWeave's Nov. 10 funding plan adds 0.3 points to capital
The moveThe data5 rows · sources
| Measure | Value |
|---|---|
| Reading before this day | 6.4 |
| This piece's move | +0.3 (Capital, reported) |
| Band for reported evidence | 0.3 to 0.8 |
| Reading after the day (with 1 other piece that day) | 7.5 |
| Distance to 100 | 92.5 |
What did CoreWeave tell lenders on Nov. 10?
Start with what closed. CoreWeave raised about $4.2 billion through an upsized offering of convertible senior notes, opened its first at-the-market program for up to 35 million Class A shares, and reported the $2.6 billion DDTL 5.5 loan facility 1. A delayed draw term loan (DDTL) lets a borrower pull cash in tranches as hardware arrives, and CoreWeave closed this one on Aug. 10 7.
Intrator then drew the line on bonds. "Looking ahead, we will not use the unsecured debt market to fund our business at current yields nor do we need to," he said on the call 2. Read the conditional: "at current yields" ties the policy to a price, so a cheaper bond market would reopen the door. Chief Financial Officer Nitin Agrawal named the replacement. "We expect asset-level debt to cover the significant majority of our remaining capital needs," he said.
Price supports the plan. Intrator gave the cost of that debt for the end of Q3: "our weighted average cost of debt across our entire business was 7.9%, down 250 basis points year-over-year" 2. The next DDTL is expected to yield 7 percent to 7.5 percent and to finance more than 90 percent of its related capex, and it should launch within weeks, according to MarketBeat's account of the call 3. That is below the 7.9 percent average.
Customers add a second source. CoreWeave expects about $9 billion in prepayments and deposits over the next three months, including more than $3 billion tied to re-contracting, and it has collected prepayments on 70 percent of this year's deals 3. Full-year capex guidance is $37 billion to $39 billion, with $23.6 billion spent through September 1. That leaves $13.4 billion to $15.4 billion for the fourth quarter by this desk's arithmetic, so $9 billion of prepayments covers about 58 to 67 percent of it.
CoreWeave's expected prepayments cover about 58 to 67 percent of Q4 capex
ComparedWhy does a skipped bond market matter to the customer?
Secured loans price the customer, because the contract is the collateral. Dave Friedman, who writes the newsletter Buy the Rumor; Sell the News, analyzed two CoreWeave loans closed 48 days apart. The first, DDTL 4.0, was $8.5 billion closed Mar. 31, rated A3 and priced at 2.25 percentage points over the secured overnight financing rate (SOFR), and it rested on one investment-grade customer. Next came DDTL 5.0, $3.1 billion closed May 18, rated Ba2 and priced at 4.50 points over SOFR, and it rested on two customers below investment grade 4.
Friedman's conclusion carries the argument of this piece. "The dominant variable separating these two facilities is the credit quality of the underlying customer contract," he wrote 4. He also stated the limit of his own case: the 225 basis point gap reflects public syndication and the rating bucket as well as customer credit. The reading holds with that caveat, because the same borrower and the same GPUs sat on both sides of the gap.
The trend continued. DDTL 5.5 priced at 5.50 points over SOFR with a five-year maturity, while its customer contracts average about three years 7. That is 325 basis points above DDTL 4.0 by this desk's arithmetic. Brannin McBee, CoreWeave's co-founder and chief development officer, put the maturity gap positively: "Lenders are now comfortable financing shorter-dated contracts, which allows us to target a wider variety of customers". Lenders now accept contracts shorter than the loan, and they charge a wider spread for it.
CoreWeave's loan spreads widen as its customers' credit weakens
TimelineThe data5 rows · sources
| Date | Event | Source |
|---|---|---|
| DDTL 4.0, $8.5 billion, rated A3, SOFR plus 2.25 | [4] | |
| DDTL 5.0, $3.1 billion, rated Ba2, SOFR plus 4.50 | [4] | |
| DDTL 5.5, $2.6 billion, SOFR plus 5.50, five-year term | [7] | |
| Bloomberg reports Microsoft reassessing neocloud contracts | [5] | |
| Q3 results: $4.2 billion converts, unsecured bonds ruled out | [1] [2] |
Who is the customer on the other side of the contract?
For CoreWeave, the answer includes Microsoft. The Next Web reports that Microsoft's leaders grew frustrated with neocloud costs and delays, turned down an option to expand an Nscale deal in Texas, pulled out of an Nscale site in the UK and is winding down a 2023 Oracle deal 5. Microsoft declined to comment, and Bloomberg's account rests on unnamed people.
Adam Levy of Motley Fool summarized the review on Nov. 13. "The tech giant is reevaluating its contracts with those companies with an eye toward reducing the number it works with," he wrote 6. Note "reducing the number": the target is a count of vendors, and Levy adds that Microsoft keeps spending with some neoclouds. Which vendors stay is undecided, and CoreWeave is among those named in the reporting 5.
Here the loan analysis and the customer reporting meet. If lenders price the customer, Microsoft's choice changes the spread on CoreWeave's next facility. The 36 percent revenue share means a single contract decision can move the credit of the whole company, which is the exposure Intrator's plan to skip bonds transfers to the loan market.

What would each side need to be true?
Intrator speaks for the plan. "And our funding is anchored by secured lending, customer prepayments and operating cash flows," he told analysts 2. The plan holds if three things stay true: lenders keep pricing near 7 to 7.5 percent, customers keep prepaying at the Q3 rate, and Microsoft's review ends with CoreWeave retained. Intrator's own evidence is the 70 percent prepayment rate and a cost of debt that fell 250 basis points in a year.
Against reading the plan as asset-backed, Friedman wrote that "What moves the rating is the customer on the other side of the take-or-pay contract" 4. His point predates the Microsoft reporting by five months, and the November reports supply the customer-side event his framework says to watch. A take-or-pay contract obliges the customer to pay for capacity whatever its use, so the contract's value depends on the customer's ability to pay through its term.
The two cases meet at one date. Intrator needs the review to end well by the time the next DDTL launches in the coming weeks 3. Friedman named his own falsifying test: a facility backed by below-investment-grade customers that prices inside SOFR plus 3.50 percent 4.

Intrator counts on secured loans and prepayments; Friedman prices the customer
Both sidesWhy is the step only 0.3?
The ledger moves capital up by 0.3 at reported confidence. Closed financing carries the step: $4.2 billion of converts, a closed $2.6 billion loan and a weighted cost of debt that fell 250 basis points 172. Backlog of $132.5 billion and more than 1.7 gigawatts of active power give lenders collateral to price.
Three facts hold the step at the bottom of the band. Interest expense of $846 million is 4.1 times operating income of $207 million, and fourth-quarter interest guidance of $1.05 billion to $1.15 billion runs 24 to 36 percent higher by this desk's arithmetic 1. The $9 billion of prepayments is an expectation for the next three months, so collection remains to be shown 3. Bloomberg reported the Microsoft review through unnamed sources, which keeps the reverse move open 5.
The strongest fact the other way is the 70 percent prepayment rate with a falling cost of debt, evidence that lenders and customers keep paying CoreWeave while Microsoft reviews. Timing answers it: the rates were set before the Nov. 6 reporting, and the next DDTL is the first price set after it. The verdict for a reader tracking the buildout: treat CoreWeave's secured debt as financing backed by Microsoft's credit as much as by GPUs, and judge the next DDTL spread before crediting a larger step.
What CoreWeave's Nov. 10 release confirms, and what stays open
The recordThe data8 rows · sources
| Column | Item | Source |
|---|---|---|
| On the record | About $4.2 billion of convertible senior notes raised | [1] |
| On the record | Weighted average cost of debt 7.9 percent, down 250 basis points | [2] |
| On the record | Prepayments collected on 70 percent of 2026 deals | [3] |
| On the record | Backlog of $132.5 billion at Sept. 30 | [1] |
| Open | About $9 billion of prepayments expected, not yet collected | [1] |
| Open | Interest expense $846 million against $207 million operating income | [1] |
| Open | Microsoft, 36 percent of Q2 revenue, reviewing neocloud contracts | [6] |
| Open | Next DDTL pricing, expected at 7 to 7.5 percent | [3] |
By the numbers
- $46.9 billion: CoreWeave's total debt at Sept. 30, 2026, with $41.6 billion of it recourse debt 1.
- 7.9 percent: weighted average cost of debt at the end of Q3, down 250 basis points in a year 2.
- $9 billion: customer prepayments and deposits CoreWeave expects in the next three months 1.
- Thirty-six percent of CoreWeave's Q2 2026 revenue came from Microsoft 6.
- Capex guidance for 2026 stands at $37 billion to $39 billion, with $23.6 billion spent through Q3 1.
- A 325 basis point rise in loan spread, from SOFR plus 2.25 points (DDTL 4.0) to SOFR plus 5.50 points (DDTL 5.5), by this desk's arithmetic 47.
- Fourth-quarter interest expense is guided to $1.05 billion to $1.15 billion, against $846 million in Q3 1.
What to watch
The terms of CoreWeave's next DDTL, due to launch within weeks, are the cleanest test: a spread near the 7 to 7.5 percent yield Agrawal expects would confirm the move, and a wider spread would reverse it. Microsoft's decision on which neoclouds stay, and any change in the 36 percent revenue share in CoreWeave's Q4 report, would show whether the review reached CoreWeave. Collection of the $9 billion of prepayments by early February would turn an expectation into closed financing.
Sources
- 1CoreWeave Reports Strong Third Quarter 2026 Results, CoreWeave, Inc., Nov. 10, 2026
- 2CoreWeave Q3 2026 Earnings Call Transcript, TradingKey, Nov. 10, 2026
- 3Transcript: CoreWeave Q3 Earnings Call Highlights, MarketBeat, Nov. 10, 2026
- 4CoreWeave Issued Yet More Debt, Buy the Rumor; Sell the News, Dave Friedman, May 28, 2026
- 5Microsoft is winding down its deal to rent AI computing from Oracle, The Next Web, Ana Maria Constantin, Nov. 6, 2026
- 6Microsoft Just Piled Onto the Bad News for CoreWeave, Oracle, and Nebius, The Motley Fool, Adam Levy, Nov. 13, 2026
- 7CoreWeave Closes $2.6 Billion Loan Facility, Expanding Financing Flexibility for AI Infrastructure, CoreWeave, Inc., Aug. 10, 2026